Overview
Nubank is a digital bank that started in Brazil and now serves customers in Brazil, Mexico and Colombia without a single branch. Its parent company, Nu Holdings Ltd., is incorporated in the Cayman Islands, run from São Paulo and listed on the New York Stock Exchange under the ticker NU. At 30 September 2026 it reported 143 million customers, nearly 120 million of them in Brazil, which makes it one of the largest financial institutions in Latin America by customer count.
History
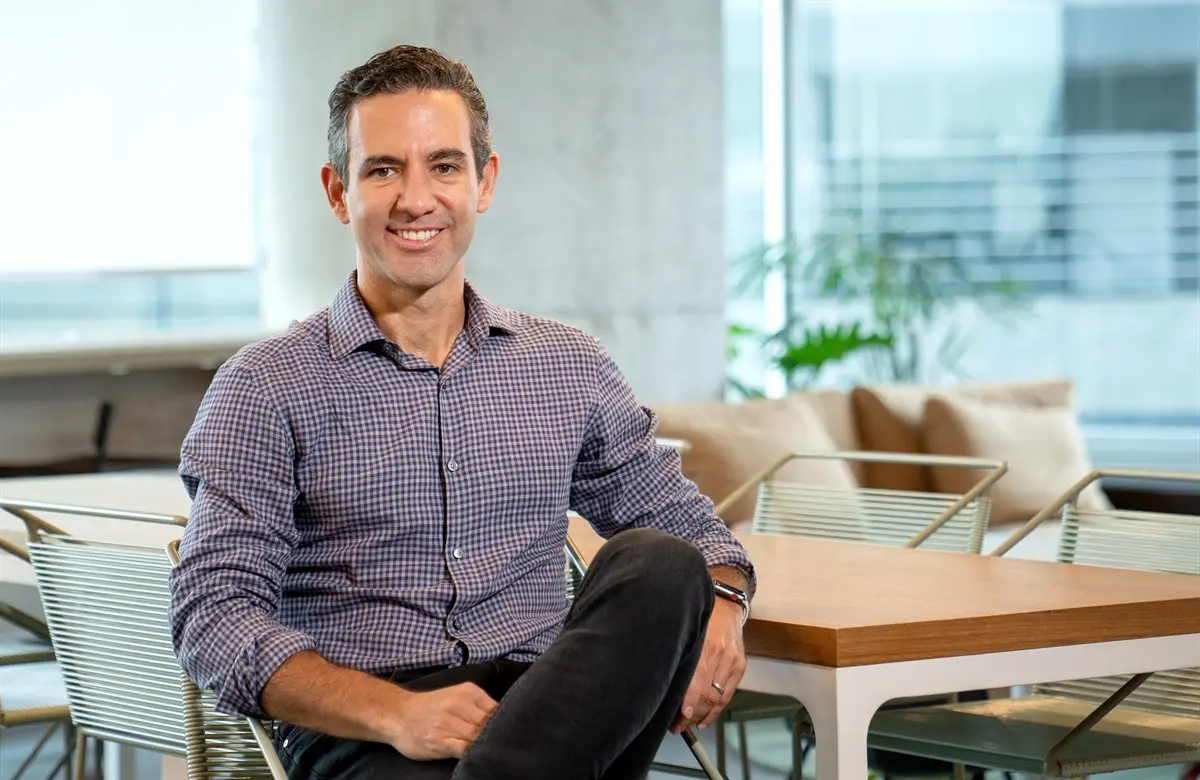
Nubank was founded in 2013 by David Vélez, a Colombian who had been sent to Brazil by Sequoia Capital to look for investments; Cristina Junqueira, who had run credit-card businesses at Itaú; and Edward Wible, an American engineer. Vélez's own starting point was his experience as a customer: opening an ordinary account in São Paulo took months of branch visits and came with high fees and very expensive credit. He read that as the sign of a concentrated market in which a few large banks faced little pressure to improve.
The first product, launched in 2014, was deliberately narrow: a purple Mastercard credit card with no annual fee, managed entirely through a phone app. From there the company added a digital account, debit cards, personal loans, investments and insurance, and expanded into Mexico and Colombia. Investors including Sequoia, Tencent, DST Global and Tiger Global funded years of losses, and Berkshire Hathaway invested US$500 million in 2021. Nubank listed in New York in December 2021 at a valuation of roughly US$41 billion.
The company lost money in 2020 and 2021, posted its first full-year profit in 2023 and has grown earnings quickly since. Its full-year 2025 results showed revenue of US$16.3 billion, net income of US$2.9 billion and 131 million customers. In the third quarter of 2026 it reported record quarterly net income of US$1.1 billion on revenue of US$6.3 billion, with a 32% return on equity.
2026 also changed its regulatory footprint. On 29 January the US Office of the Comptroller of the Currency gave conditional approval for a new national bank, Nubank, N.A., which still needs Federal Reserve and FDIC approvals and must open within 18 months (company announcement). In July Mexico's banking regulator granted Nu México final authorization to operate as a commercial bank, and the third quarter was its first as one.
How the business works
Nubank earns most of its money the way banks always have: interest on credit cards and loans, card interchange fees, and the spread between what it pays on deposits and what it earns on lending. What differs is the cost base. With no branches and software handling most customer service, its cost to serve each customer is far below that of incumbents with large physical networks. The company reported an efficiency ratio of about 19% in the third quarter of 2026. That cost advantage lets it drop many of the fees customers dislike while still making money.
The model depends on two things working together. Low acquisition costs, driven largely by word of mouth, bring in customers cheaply. Data from those customers' accounts then helps Nubank decide whom to lend to and how much. Deposits, which reached US$47.5 billion at 30 September 2026, fund a growing share of that lending.
The risk sits in the same place. Lending quickly to people with thin credit histories produces defaults, and Nubank's share of loans more than 90 days overdue rose to 7.3% in the third quarter of 2026, from 6.9% the quarter before. For a lender, loan quality matters more than customer counts.
Ownership and leadership
Nu Holdings is a public company, but it is controlled by its founder. Its Class B shares carry 20 votes each, against one vote for a Class A share. According to the company's FY2025 annual report on Form 20-F, Vélez held 88.3% of the Class B shares and 74.4% of total voting power, enough to decide most shareholder votes while owning a much smaller share of the economics.
Vélez is founder and CEO. Junqueira has moved to the United States to lead the US business, and Roberto Campos Neto, a former president of the Central Bank of Brazil, is to chair the US bank's board.
Controversies
PROVEN: the 2020 diversity remarks. In October 2020, Junqueira said on the Brazilian television programme Roda Viva that the company could not "lower the bar" in hiring, in a discussion of recruiting Black employees. After a public backlash, the three founders published a letter titled "O Nubank errou" ("Nubank got it wrong"), apologising and promising a racial-diversity programme, as CNN Brasil and other outlets reported. The facts of the remark and the apology are not in dispute.
ALLEGED: over-indebtedness claims in Bahia. The public prosecutor's office of the Brazilian state of Bahia has filed a civil action accusing Nubank of credit practices that push consumers into over-indebtedness, according to Bahia Notícias and other regional outlets. Nubank disputes the allegations and says it complies with consumer law. We found no court ruling against the company in the case, and the claims remain unproven.
Why it matters
Nubank is the clearest evidence that a protected, profitable banking market can be opened up when technology removes the costs that justified high prices. It brought tens of millions of Latin Americans into formal banking, and its profits have answered years of doubt about whether the model could last. The next tests are harder: keeping loan losses under control as it lends to riskier customers, and proving the model travels to Mexico and the United States. For the founder's story, read David Vélez: The Banker Who Attacked Brazil's Banking Oligopoly.